Separate what you earn for working from what you receive as an owner
Salary, bonuses, dividends, minimum cash and scenarios in a single forecast. USD, relative months 1–60. Revenue is collected and costs, estimated tax, capex and salary are paid in the same month. Original payroll excludes the founder. Financing, depreciation and employer charges are not modeled.
One-time payment
$19
Hosted checkout by Recurrente · immediate on-site fulfillment after payment confirmation · 15-day refund period.
Recognize the problem
Three signals that the current approach is costing clarity.
Poorly structured compensation can hide whether the business truly supports its founder.
Inputs are not connected to the decision.
The example does not explain how to customize it.
Practical outcome
Separate pay for work, performance bonuses and returns as an owner.
What is included
The working pieces, connected.
Minimum scope
Workbook de 60 meses, tres escenarios y política editable.
Safe preview
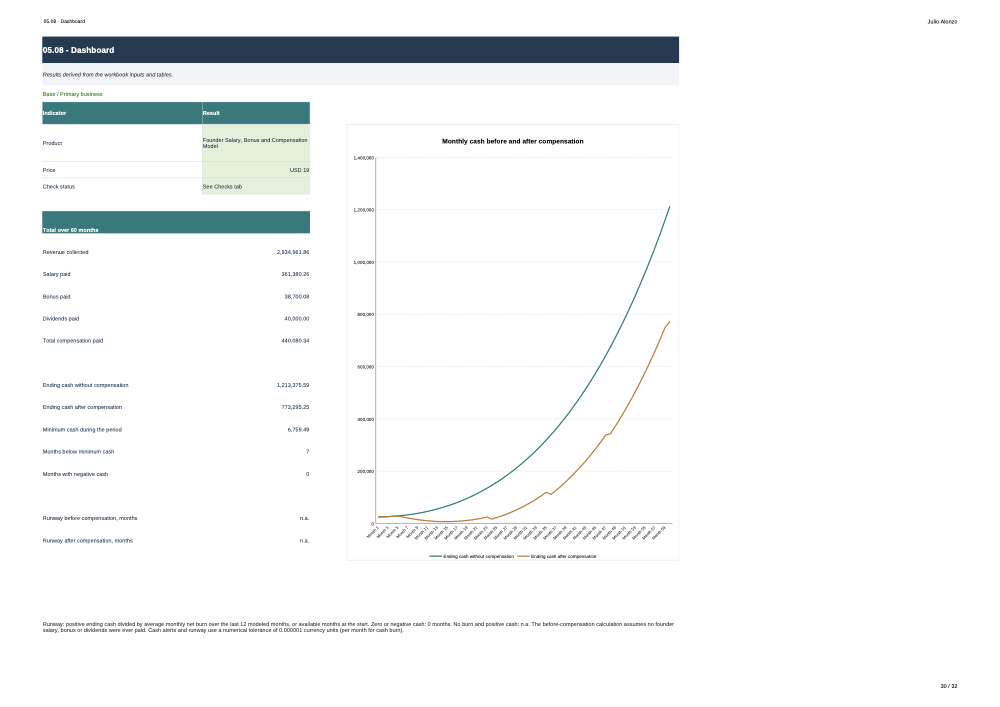
Monthly and annual compensation and its effect on cash runway. USD, relative months 1–60. Revenue is collected and costs, estimated tax, capex and salary are paid in the same month. Original payroll excludes the founder. Financing, depreciation and employer charges are not modeled.
The preview shows structure and a limited example; it does not expose the complete paid editable or delivery file.
How it works
From context to a reviewable output.
- 1
Define the context and decision.
- 2
Complete the required inputs.
- 3
Produce a first working version.
- 4
Review, validate and adapt.
This is for
Consultants, agencies, family businesses, digital retailers, microbusinesses and independent professionals.
This is not for
It is not for anyone seeking guaranteed results, regulated advice or a file that works without data or review.
Method and limits
Useful when judgment stays in the loop.
Methodology and author
Define context, complete inputs, produce, review and adapt. Designed and signed by Julio Alonzo. Designed and signed by Julio Alonzo.
Requirements and limitations
USD, relative months 1–60. Revenue is collected and costs, estimated tax, capex and salary are paid in the same month. Original payroll excludes the founder. Financing, depreciation and employer charges are not modeled. The tax rate is an editable revenue-based assumption, without local tax calculation. Bonus surplus deducts variable costs, fixed expenses, payroll, estimated tax and salary; it excludes capex and bonus. It does not necessarily equal accounting or taxable profit. Initial monthly salary: USD 4,000 / 6,000 / 7,500, derived from the original annual illustrations of 48,000 / 72,000 / 90,000. Default start: month 6. A 5% increase applies every 12 months from that start, first in month 18. Salary is paid even if it creates negative cash; the funding need is shown. Bonus only in months 12, 24, 36, 48 and 60. Mode 1: positive annual surplus × rate × time share, limited to annual cap × time share. Mode 2: annual cap × the lower of attainment and 100% × time share. Original amounts 0 / 12,000 / 25,000 are interpreted as editable annual caps. Bonus is paid only from cash above the minimum. Dividends: annual company request × ownership; paid after bonus without reducing cash below the minimum plus a default additional USD 0.01 reserve. Unpaid targets do not carry forward and do not represent recognized liabilities. Original dividend requests of USD 0 / 10,000 / 30,000 are retained as editable annual company pools. The positive additional reserve respects the policy requiring post-payment cash to exceed the minimum. Legally distributable profit is not determined and no payment is authorized. Three businesses: total time shares 100%; individual ownership between 0% and 100%. Salary and bonus are allocated by time share; dividends by ownership. The business selector changes that allocation. Operating inputs must describe the chosen business; three business forecasts are not stored and there is no automatic consolidation. The three-scenario comparison is live and uses shared monthly factors with visible annual calculations. It shows year-end positions and does not guarantee liquidity within each month. The 60-month detail covers only the selected scenario and business; checks reconcile all five years. Runway: positive ending cash divided by average monthly net burn over the last 12 modeled months, or available months at the start. Zero or negative cash: 0 months. No burn and positive cash: n.a. The before-compensation calculation assumes no founder salary, bonus or dividends were ever paid. Cash alerts and runway use a numerical tolerance of 0.000001 currency units (per month for cash burn). The complete original policy and documents are retained. Their brackets require approval and local adaptation; editing them does not change numeric inputs. Data is fictional, and original dates and QA are historical. Use this methodology and this edition's report for the repaired calculations. The native Microsoft Excel interface was not tested.
Cutoff date: 2026-10-12
FAQ
Before purchasing.
Answers derived from the product file and its commercial kit.
Secure purchase
Pay at Recurrente. Download here.
The Site never receives card data. Recurrente confirms the payment by signed webhook and this page releases only the files linked to that paid session.
$19
- ✓ One-time payment in USD
- ✓ Verified ZIP package
- ✓ 15-day refund period
- ✓ Support by email
Same system